Max yourIncome
Money you can use while you are alive
An indexed universal life policy builds cash value tied to a market index with a floor of zero. You can borrow against it, tax-free, for retirement, a down payment, or a rough year.
Independent life insurance, licensed in ten states.
Life insurance that protects your family if you are gone and builds money you can use while you are here. Jeremy Jones shops several A-rated carriers and shows you the real numbers, for free.
The name is the plan. Most people buy life insurance for what happens after. The policies Jeremy writes are built to do something for you before.
Max yourIncome
An indexed universal life policy builds cash value tied to a market index with a floor of zero. You can borrow against it, tax-free, for retirement, a down payment, or a rough year.
Max yourImpact
If something happens to you, the people who depend on you get a tax-free check within weeks. The mortgage gets paid. The kids stay in their school. Nobody sells the house.
Max yourLife
Most of the policies Jeremy writes let you access part of your coverage early if you are diagnosed with a critical, chronic, or terminal illness. It is money for treatment, not just a payout after.
LifeMaxxing is independent, so the recommendation follows your budget and your health, not one company's product shelf.
Where most clients start
Permanent coverage with a cash value account that grows with a market index and never loses money in a down year. The policy most of our clients start with.
The most coverage for the least money, for a set number of years. Built for the stretch when the mortgage is big and the kids are small.
A policy written around your loan balance and the years left on it, so the house stays in the family instead of going on the market.
A smaller whole life policy sized to the funeral, the last medical bills, and the month after. No exam, rate locked for life.
What you already have, who depends on you, and what you want the money to do. No forms to fill out first and no pitch.
LifeMaxxing is independent. Jeremy shops several A-rated carriers and shows you the actual quotes, including the ones that are not the right fit and why.
Most applications are approved without an exam, many within a few days. You get the policy, your family gets the beneficiary letter, and Jeremy stays your agent for the life of it.
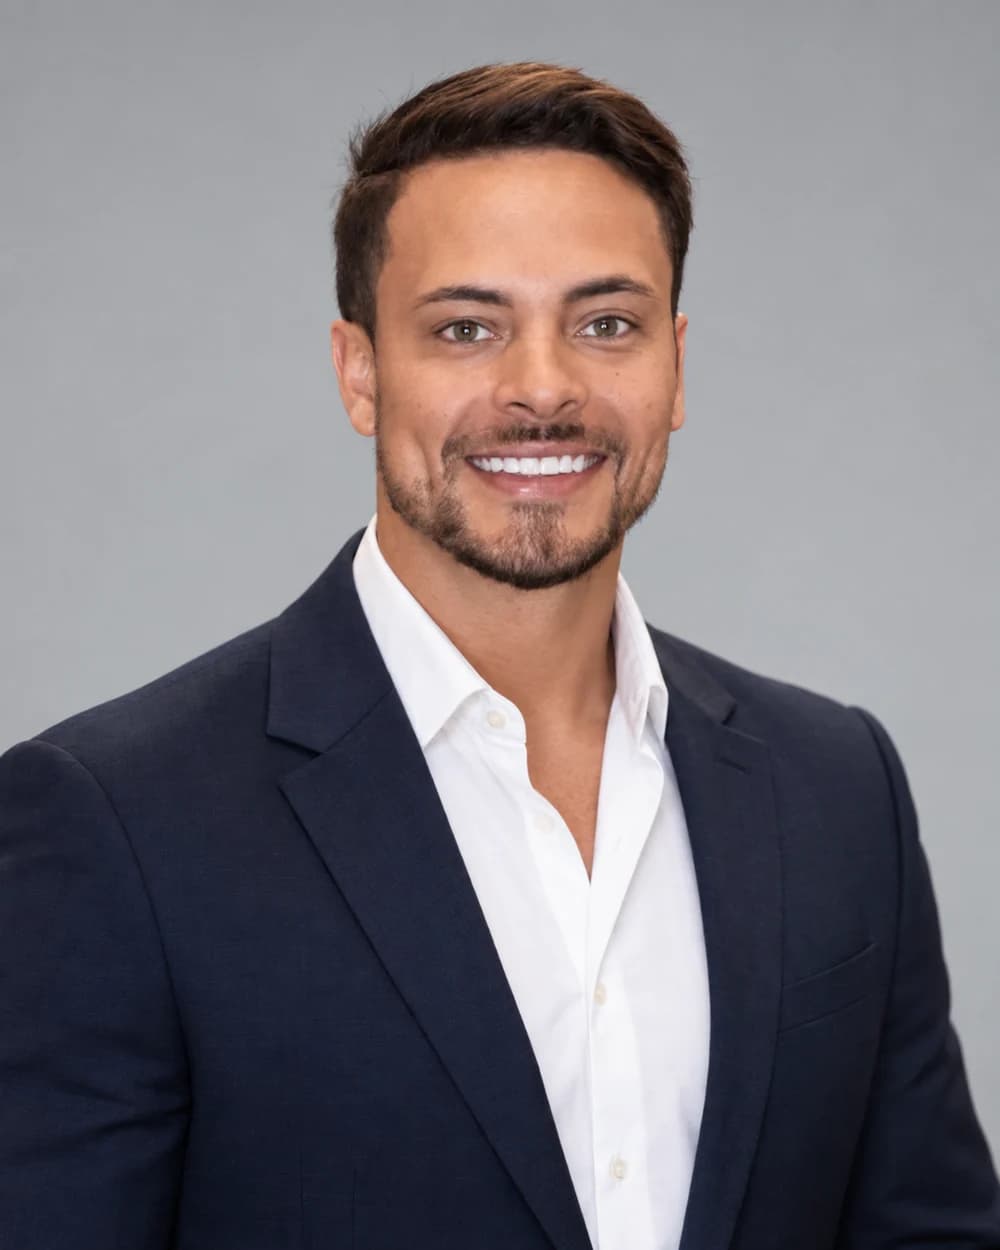
Founder of LifeMaxxing and a licensed life insurance producer in ten states, based in South Carolina.
Jeremy got into this business because most people he knew were either uninsured or paying for a policy nobody had ever explained to them. He does the opposite: one conversation, the actual quotes from several carriers, and a plain answer about what each one does and does not do. If none of them are right for you, he will say so.
He works with families who want two things at once: the certainty that the people they love are taken care of, and a policy that builds something they can use themselves.
Jeremy can write and service a policy in any of these states, almost always by phone and e-signature.
Every quote is compared across A-rated companies. You see the ones that fit and the ones that do not.
It is permanent life insurance with a savings account attached. Part of your premium pays for the death benefit and part goes into a cash value account that earns interest based on a market index like the S&P 500. When the index goes up, your account is credited, up to a cap. When it goes down, you are credited zero instead of losing money. You can borrow against that cash value tax-free, which is how people use it for retirement income.
No. It is life insurance. The cash value is a feature of the policy, not a brokerage account, and it is not a substitute for a 401(k) or an IRA. It is best for people who already max out those, or who want a death benefit anyway and would rather the premium build something than disappear.
For most of what Jeremy writes, no. You answer a set of health questions and many people find out within days whether they are approved. Larger coverage amounts sometimes require a quick paramedical exam at your home or office, and he will tell you up front if yours does.
It depends on your age, health, tobacco use, and how much coverage you want. Term life for a healthy person in their thirties is often under a dollar a day. Indexed universal life costs more because it builds cash value. Rather than guess, Jeremy runs your real numbers with several carriers and shows them to you side by side, for free.
Usually, yes. Diabetes, high blood pressure, and a past cancer diagnosis are all conditions carriers place regularly. Some will cover you from day one; others use a waiting period. Jeremy will tell you plainly which one you are looking at before you sign anything.
No. Jeremy is licensed in ten states and nearly everything is handled by phone, video, and e-signature, usually in one appointment. If you are in South Carolina and would rather sit down, that can be arranged.
No. LifeMaxxing is an independent agency. We are not a carrier and we are not affiliated with any government agency, Medicare, or the Social Security Administration. Jeremy is paid a commission by the insurance company if you take a policy, which is worth knowing up front.
Two short steps. Jeremy calls you back within one business day with quotes from several carriers and no pressure to take any of them.
Monday to Saturday, 9am to 8pm Eastern